
24th July. As Red Sea hostilities continue to force widespread maritime diversions around the Cape of Good Hope, leading bunker company Peninsula is warning of a “perfect storm” for global tanker operators.
The unprecedented surge in tonne-mile demand is now intersecting with stringent Mediterranean emissions regulations, threatening to more than double operational costs and severely tighten bunker supply at alternative key ports.
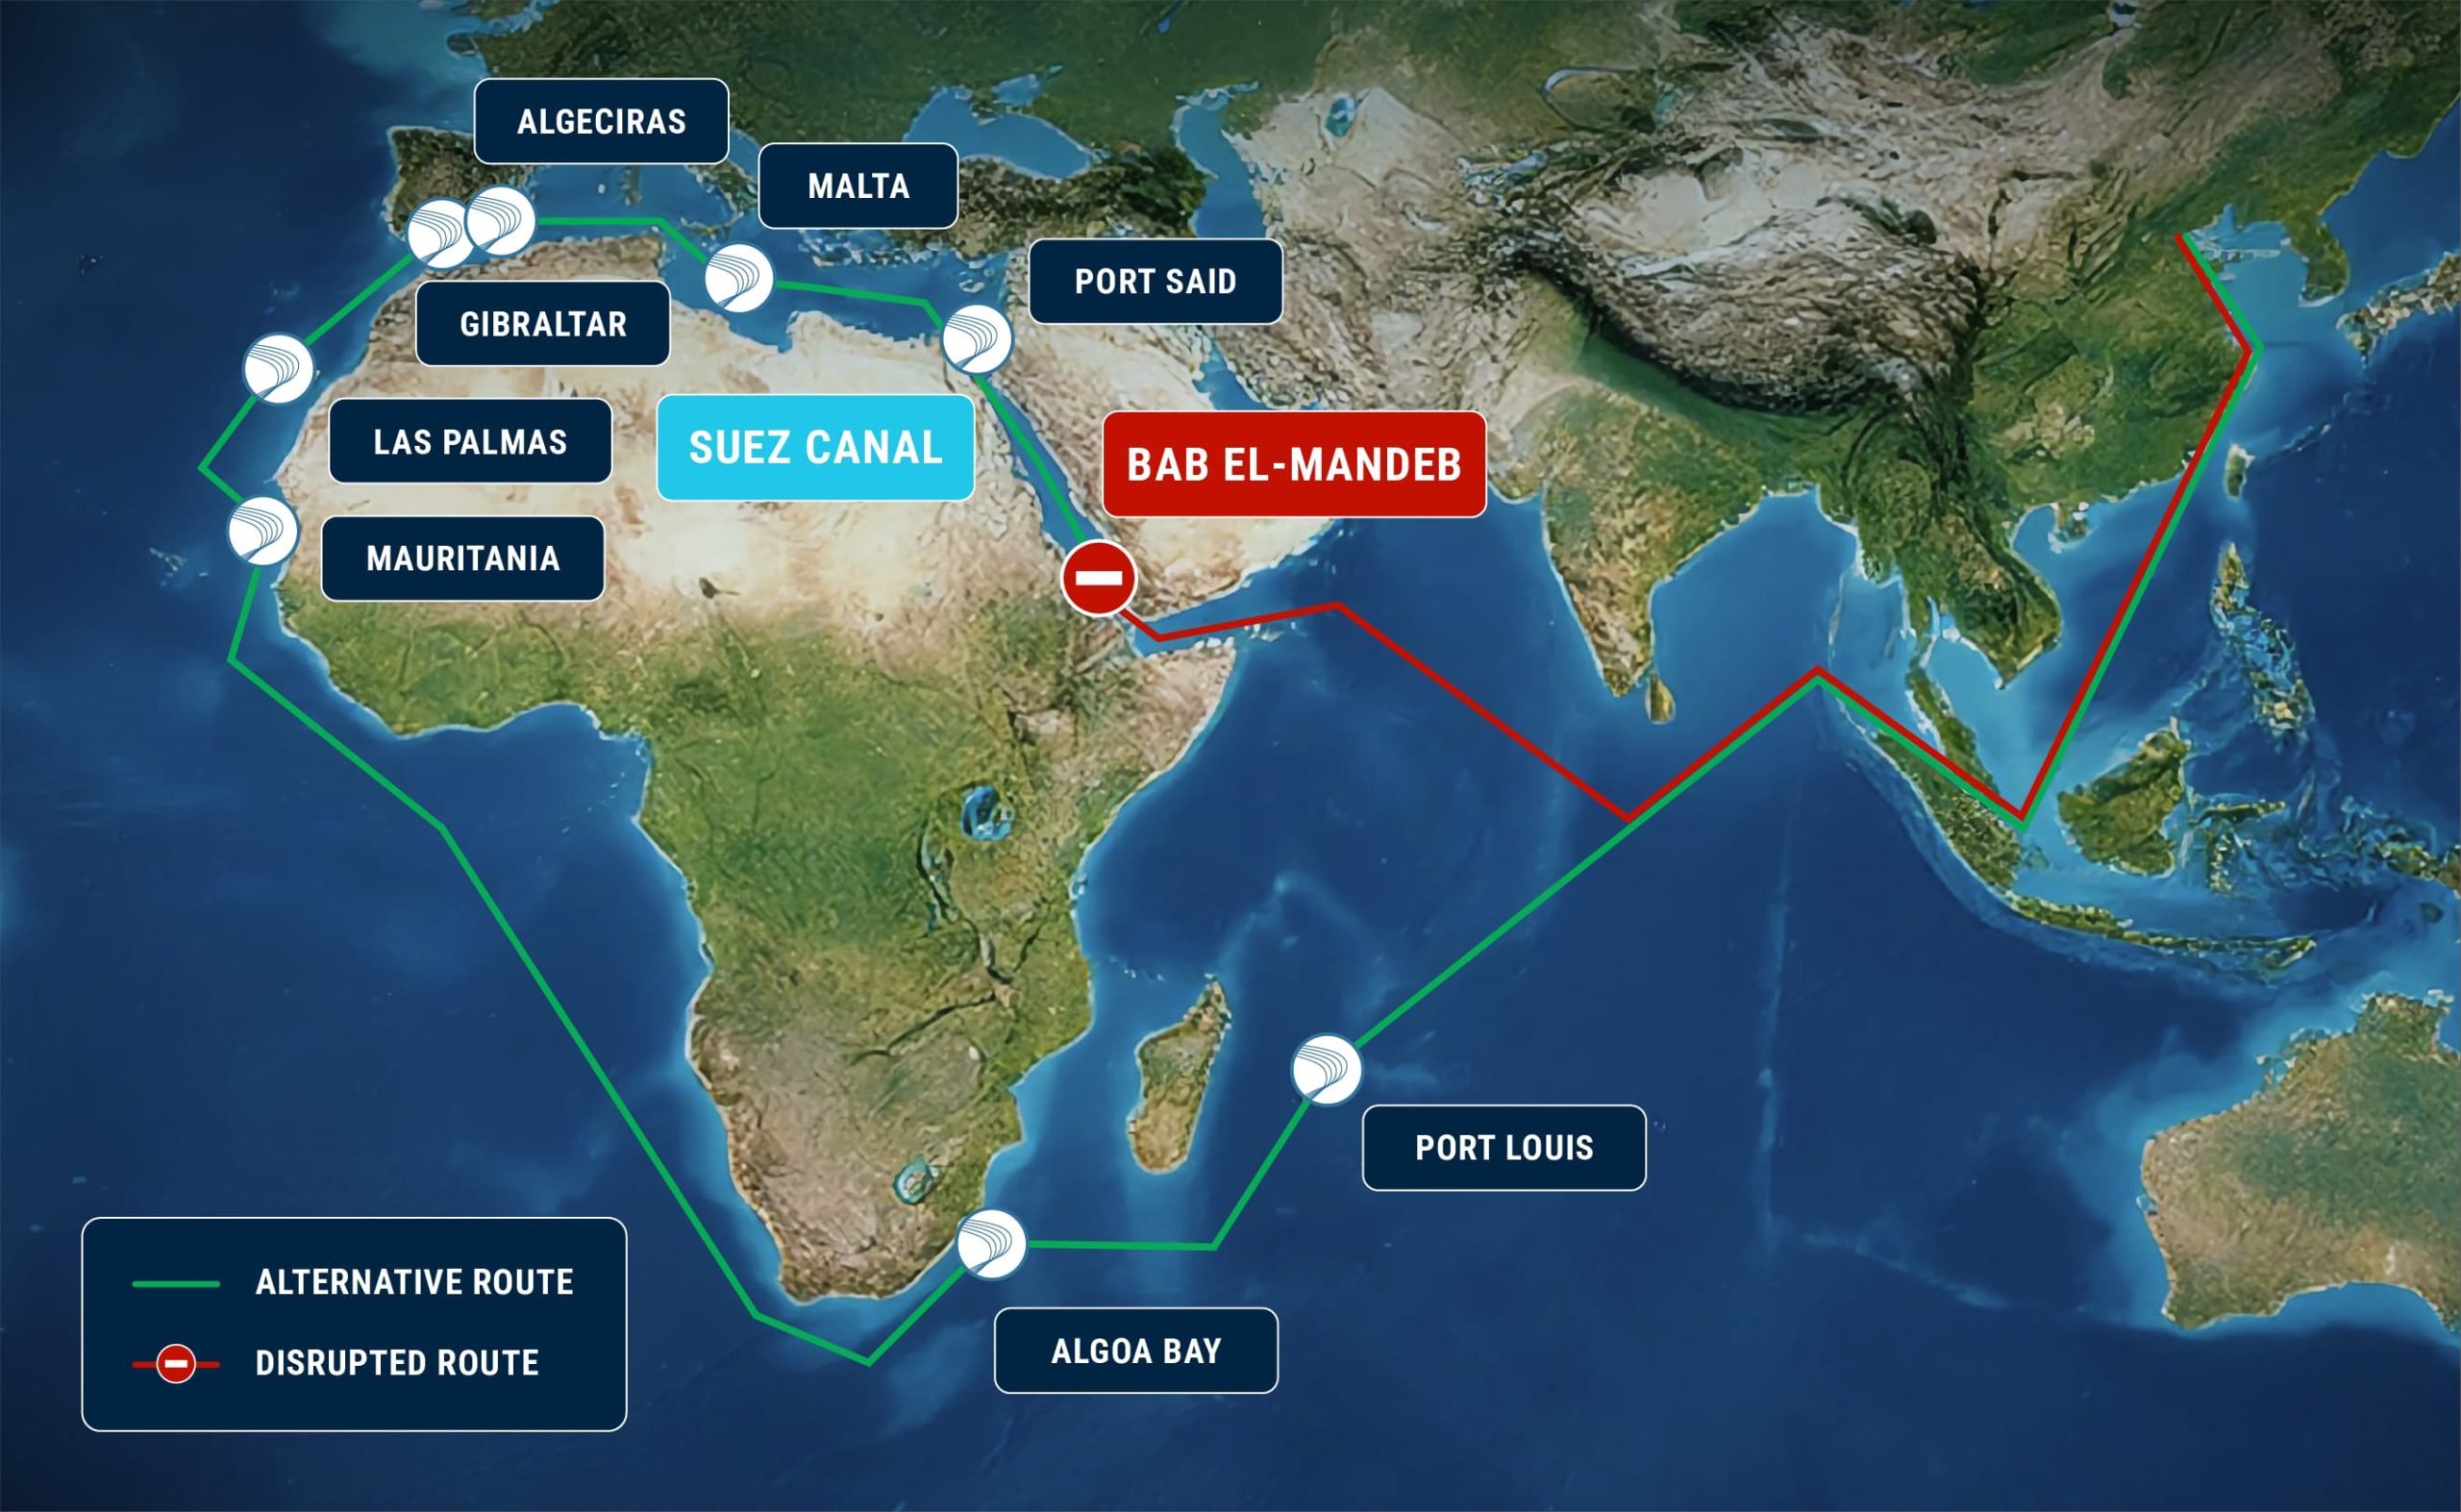
With the Bab el-Mandeb Strait increasingly bypassed, vessels are exiting the Red Sea via the Suez Canal and navigating westbound through the Mediterranean to reach Asia.
Peninsula notes that this detour could more than double the normal tonne-mile demand of a Bab el-Mandeb eastbound exit. For a typical Suezmax tanker, the diversion will require around 1,500 tonnes of additional fuel, at a cost of circa $800,000 and an emissions cost of roughly 3,800 tonnes of CO2.
Spot rates for Suezmax vessels – the largest tankers that can transit the Suez Canal fully laden – are already increasing, causing a scramble to cover the cargoes before the tonne-mile effect kicks in.
Kenny MacLean, Chief Operations Officer at Peninsula, said: “The industry could be dealing with a sudden, significant increase in fuel consumption. This is more complex than simply plotting a longer course – it will require a fundamental recalibration of voyage economics that will squeeze global bunker supply at a time when demand already outstrips supply.”
Beyond the raw cost of fuel, Peninsula is highlighting a critical regulatory blind spot for rerouted vessels: the Mediterranean Emissions Control Area (MedECA). Under these rules, vessels transiting the entire Mediterranean must burn fuel with a maximum sulphur content of 0.1%, rendering standard Very Low Sulphur Fuel Oil (VLSFO) non-compliant.
With European authorities increasingly deploying “sniffer drones” to remotely analyse vessel emissions in real-time, operators must switch to compliant Marine Gas Oil (MGO) or suitable biofuels before entering the region. Failure to secure compliant fuel risks severe fines and costly vessel detentions.
The sudden shift in maritime traffic could redraw the global bunkering map. Peninsula expects significantly increased demand in alternative physical supply ports along the revised route, including Port Said, Malta, Gibraltar, Algeciras, Las Palmas, Algoa Bay, and Port Louis.
Richard Alvarez, Global Head of Sales at Peninsula added: “Operators are navigating a regulatory and logistical minefield. Securing compliant fuel conveniently, in the right location, in a rising price environment is now the defining challenge of these deviated voyages.
“As supply tightens at alternative bunker hubs, the ability to rely on suppliers with a globally integrated supply network and deep access to multi-product cargos will prove critical to minimise disruption and avoid the costs of non-compliance.”
12th August. As a brief update to our above article, the situation in both Bab el-Mandeb and the Strait of Hormuz remains largely unchanged.
The world continues to contend with a challenging “dual chokepoint” scenario. Negotiations around the conditional opening of Hormuz appear to be weighted towards Iran’s demands, with Gulf states potentially becoming resigned to ceding some degree of control over the strategic waterway. Meanwhile, in the Red Sea, Houthi attacks have focused on Saudi Arabian-controlled assets and infrastructure, highlighting the continued reach of the Islamic Republic’s proxies.
The key question for shipping, and by extension bunkering, is whether we are entering an era in which dual chokepoint disruption becomes a persistent feature of global trade.
Such a scenario would place additional pressure on voyage planning and increase complexity across areas including crew safety, insurance, financing of vessels and cargoes, and the environmental impact associated with longer voyages and higher emissions.
In this “age of disruption”, intelligent solutions will demand greater flexibility in marine fuel procurement across a diversified network of ports. Contracts, to secure product availability in tighter supply conditions, will become more prevalent, often with port optionality built in to support dynamic route planning when trading or geopolitical conditions change. Supply chain resilience will become the critical factor instead of price.